What Documents Do You Need Before Making an Offer on a House?
Get ready for a bank statement mortgage by organizing deposit records, business documents and proof of funds before submitting a home purchase offer.
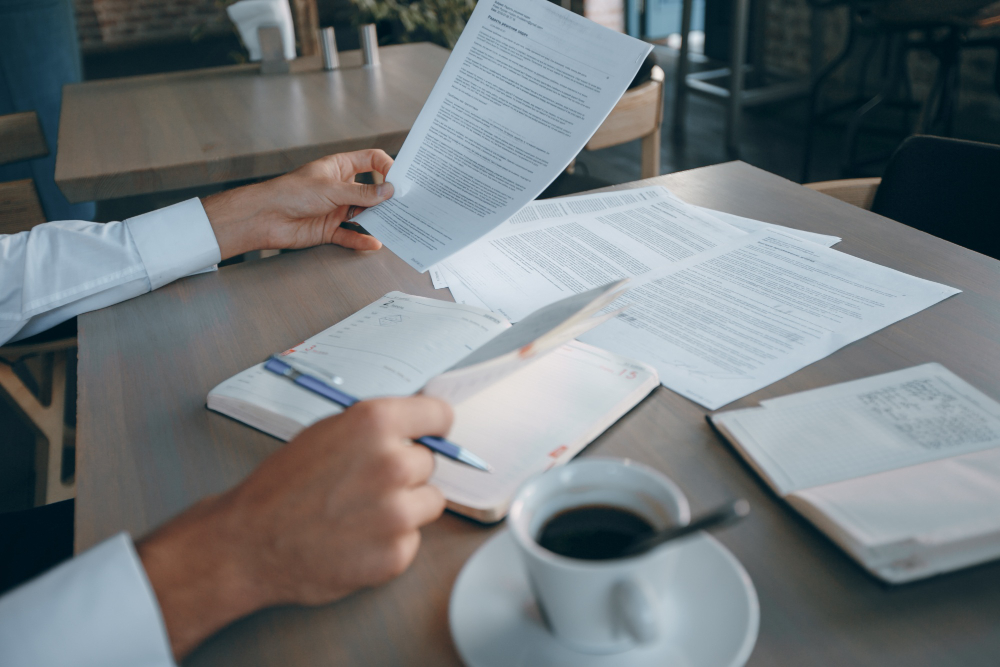
Before you make an offer, you need three kinds of paperwork: proof of your money, proof of your income, and the documents that go to the seller. Bank statements show up in all three. A standard loan usually asks for two months. A bank statement mortgage can ask for twelve or twenty-four. Either way, the bank statement for home loan packet you send decides how fast your file moves.
Bank statement mortgage or standard loan: which paper trail applies to you?
1. Standard loans lean on pay stubs and tax returns
If you work a regular job, a lender proves your income with pay stubs, W-2s and tax returns. Your bank statements play a smaller role. They show where your down payment came from and that the money has been in your account for a while. Two months is the common ask.
2. A bank statement mortgage leans on deposits
Self-employed buyers often write off enough that their tax returns understate what they earn. A bank statement mortgage reads your deposits over 12 or 24 months instead and estimates your income from them. Which path applies to you? If you collect a paycheck, the first. If you run a business and your returns look thin, ask about the second.
Documents every buyer needs
1. ID and basic details
A government photo ID and your Social Security number come first. Lenders also ask for your current address, your employer's name and address, and your work history for the past two years. None of it is hard to find. All of it slows you down if you wait.
2. Proof of income
W-2 employees send recent pay stubs, usually covering the last 30 days, plus W-2s and tax returns from the past two years. If you earn commissions, bonuses or overtime, lenders want the history behind that pay. A bonus you earned once rarely counts.
3. Proof of cash
Your lender wants to see the money for your down payment, closing costs and any required reserves. That means statements for checking, savings and any investment or retirement accounts you plan to use. Gift funds need a signed gift letter and a paper trail for the transfer.
How many months of statements
Most standard loans ask for the two most recent months, and every page of every statement. A blank-looking page still counts. Self-employed programs can ask for far more, which we cover next.
Extra paperwork for self-employed buyers
1. Twelve or twenty-four months of statements
A lender using deposits to calculate income wants a long window, commonly 12 or 24 months. Pull every statement for every account you want counted. Missing even one month can stall the file. A bank statement for home loan applications that skips months looks like a bank statement with something to hide, even when it isn't.
2. A profit and loss statement or CPA letter
Some programs want a year-to-date profit and loss statement. Others accept a letter from a CPA or tax preparer that confirms how long you've been in business and states your expense ratio. That ratio can change how much income the lender counts, sometimes by a lot.
3. Proof your business exists
Expect to show a business license, a state registration, or another record that confirms you own the company. Partners need an ownership breakdown. Lenders may count only your share of the income.
Personal vs. business accounts
Many programs accept either. Personal statements are read more directly, and business statements usually take an expense factor. Which one gives you more income depends on how you pay yourself, so ask your lender to run both before you choose.
Documents that go with the offer itself
1. The pre-approval letter
This letter says a lender reviewed your documents and expects to lend you up to a stated amount. Sellers and agents trust it far more than a quick prequalification, because someone verified the numbers. Get it before you tour homes.
2. Proof of funds
Your agent often attaches a recent bank statement to the offer to show you have the down payment. A letter without proof of cash looks half done, especially when several buyers compete for one house.
3. Earnest money receipt
Earnest money is a deposit, often 1% to 3% of the price, though it varies. It's credited toward your down payment at closing. You'll want a receipt or wire confirmation once it lands in escrow.
4. The purchase agreement
In California, agents commonly use the C.A.R. residential purchase agreement. It spells out price, deposit, contingencies and timelines. Read it. Ask questions before you sign, not after.
What lenders look for on your statements
1. Steady deposits
Underwriters read statements like a story. They want a pattern. Income can rise and fall, especially for owners, and that's fine. What matters is that the full picture holds up across the months they review.
2. Large or odd deposits
A big deposit that doesn't match your usual income draws questions. That's true on a two-month review too.
How to source a deposit
Keep proof: a sale contract, a gift letter, a paid invoice or a transfer record between your own accounts. The clearer the paper trail, the shorter the back-and-forth.
3. Overdrafts and returned payments
A single slip happens. A pattern suggests cash flow trouble. If you had a rough month, be ready to explain it in a sentence or two.
A worked example on a $750,000 offer
These numbers are illustrations, not quotes. Rates, taxes and insurance vary.
1. The payment
Say you offer $750,000 with 20% down, which is $150,000. Your loan is $600,000. At an illustrative 7.5% on a 30-year fixed loan, principal and interest run about $4,195. Add $1,000 for taxes and insurance and your full payment is about $5,195.
2. The income the lender needs
Suppose you carry $800 a month in other debts and the lender allows a 43% debt-to-income ratio. Your total monthly debts would be about $5,995, so you'd need roughly $13,940 a month in qualifying income. On personal statements with no expense factor, you'd need about that much in eligible monthly deposits. On business statements with a 50% expense factor, you'd need nearly $27,900 a month in deposits. Same house, double the deposits.
3. The cash to document
Beyond the $150,000 down payment, closing costs often run roughly 2% to 3% of the price, or $15,000 to $22,500. If the lender wants six months of reserves, that's about $31,200 more. Your total cash to show comes to roughly $196,000 to $204,000. Your earnest deposit is part of the down payment, not an extra cost.
Mistakes that stall an offer
1. Moving money around
Transfers between accounts, cash deposits and sudden large deposits raise questions. Each needs a paper trail. If you must move money, keep a record of why.
2. Sending partial statements
Page two of four isn't a statement. Download the full PDF and send every page.
3. Mixing personal and business money
If groceries and client payments share one account, the lender has to untangle them, and the file slows down. Separate accounts make your income easier to read. Pick a clean setup now, not the week before you apply.
Get your folder ready this week
1. Download full statements
Log in and download every statement you'll need, personal and business. Name the files by month so you can find them fast.
2. Write a note for every odd deposit
Scan each statement and flag anything unusual. Attach a short explanation and proof. It takes an hour and saves days.
3. Get pre-approved before you tour
Ask your lender what they need and how they'll count your income. The Taylor Weiner Team offers non-QM programs for self-employed buyers, and Taylor Weiner has 20 years of mortgage experience, a 5.0 rating on Google, and 450+ five-star reviews. Reading what past clients say about communication helps when you're weighing lenders.
Conclusion
1. Your next step
Gather your ID, income documents and full bank statements, and add the extra paperwork if you're self-employed. A standard loan usually wants two months of statements. A bank statement mortgage asks for a year or two, so start pulling them now. Get your pre-approval letter before you make an offer, and keep every deposit explainable. A clean bank statement for home loan files moves faster than a messy one, and speed wins houses.
Frequently Asked Questions
Experienced California mortgage professionals helping homeowners purchase, refinance, or access home equity with clear guidance and responsive service.
Comments (0)