How One Small Accident Can Shut Down a Business Without Coverage
See how one small accident can shut down a business without the right business accident insurance, plus smart ways to stay protected.
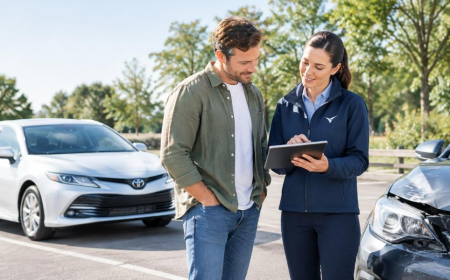
One small accident can shut down a business when there is no business accident insurance in place to absorb the cost. A customer injury, property damage claim, employee mistake, or temporary closure can quickly lead to legal expenses, medical bills, repair costs, and lost income. Many businesses can handle a minor disruption, but not the full financial impact that follows. At Insure Your Company, we help business owners understand these risks and match coverage to daily operations. This article explains how small accidents create major losses, why businesses face the most exposure, and why proper coverage matters.
What Happens When A Business Has An Accident Without Coverage?
If an uninsured business experiences a loss, the owner takes a hit on the head for every dollar that it loses. No carrier to defend against claims or pay for downtime, and cash reserves get depleted quickly.
What Are The Effects Of An Uninsured Loss On The Business?
-
Direct Costs: Medical expenses, property damage, and replacement costs are paid by the business, and there is no contribution by the carrier.
-
Defense Costs: Attorney's fees and court costs quickly add up even if the business ultimately prevails in court.
-
Downtime Losses: When doors are closed, there's lost revenue - and the bills still come in for rent, salaries, and fixed expenses.
-
Personal Exposure: If the business does not have the resources to cover the entire loss, owners can use their personal capital or resources.
Can One Injury Lawsuit Cripple a Small Business?
Yes - a single bodily injury case can wipe out a small business's cash reserves. Medical payments, legal defense, and potential settlements are generally included within general liability insurance when a customer slips or trips, or a visitor is injured.
Why Is Injury Claims So Risky?
-
Medical Payments: Injury treatment costs can rise quickly, especially when surgery or ongoing care is needed.
-
Legal Defense: Even weak claims can trigger attorney fees, depositions, and court appearances.
-
Settlement Risk: Large settlements or jury awards can exceed what a small business can afford.
-
Slip, Trip, Injury Liability: Daily foot traffic creates ongoing risk of customer or visitor injuries.
How Can One Mistake Become A Risk To A Business Shutting Down?
One slip-up - late, a coding mistake, bad advice - can trigger a lawsuit alleging actual economic damage. General liability will not come into play here; professional liability or E&O may take over.
What Are The Service Errors That Cause Shutdown Exposure?
-
Errors and Omissions: The client states that there is a mistake or missing detail in your work and it causes financial damage to the client.
-
Negligence Claims: Your clients claim that your service was not at the level that they reasonably expected and paid for.
-
Financial Harm Claims: Revenue you lost due to a mistake, and is related to your client, can equal a damage amount that will make a small company gasp.
-
High Risk Fields: The risk of E&O exposure is almost universal for consultants, IT firms, staffing agencies, and contractors.
What Are The Hidden Costs That Make Small Accidents So Expensive?
Don't let the headline figure fool you. The obvious repairs or medical costs are merely the first of numerous hidden costs that quietly compound the financial impact of business accidents.
What Are Some Of The Owners' Hidden Costs?
-
Litigation Costs: Attorney retainers and litigation expenses are legal defense fees that are incurred if the business resolves the dispute, wins, or loses.
-
Deductibles and Retentions: Self-insured retentions and deductibles require the company to pay significant sums in advance of coverage responding.
-
Lost Income: No one gets paid during downtime, and bills for payroll, rent, and loans continue to come in for the week.
-
Reputation Damage: When it becomes evident that there's a problem, negative reviews and lost customer trust push them away long after the issue is addressed.
What Are The Businesses Most Likely To Be Shut Down By A Minor Accident?
The severity of risk is not necessarily a result of the number of people. Businesses with employees going into the public, service crews moving about, data that's exposed, and services that deal with clients carry outsized business accident risks, proportionately.
Who Is Best Advised To Monitor Exposure Carefully?
-
Technology Firms: Data handling, client deliverables, and professional advice create multiple liability exposures.
-
Staffing Agencies: Multiple job sites increase exposure to employee injuries, theft, and service-related errors.
-
Contractors & HVAC: Physical work, jobsite hazards, and vehicle use increase injury and property damage risks.
-
Mobile & Data Businesses: Vehicle use and customer data create significant auto and cyber exposures.
What Coverage Gaps Commonly Leave Small Businesses Exposed?
Gaps exist because coverage is not current with the way the business is operating now. The table below matches each of these gaps with the business liability coverage that fills the void.
|
Coverage Gap |
What It Leaves Exposed |
Coverage That Closes It |
|
No general liability |
Customer injuries and third-party property damage |
General Liability Insurance |
|
No workers' comp |
Employee injuries, medical bills, lost wages |
Workers' Compensation |
|
No commercial auto or HNOA |
Crashes in owned, rented, or personal vehicles |
Commercial Auto / Hired & Non-Owned Auto |
|
No cyber liability |
Data breaches, ransomware, notification costs |
Cyber Liability Insurance |
|
No umbrella/excess |
Claims that blow past primary policy limits |
Umbrella / Excess Liability |
|
No fidelity/crime |
Employee theft or third-party dishonesty losses |
Fidelity / Crime Bonds |
|
Underinsured limits |
Severe claims that outpace low policy limits |
Higher limits + endorsement review |
How Can A Company Calculate The Actual Price of Being Underinsured?
Owners who don't consider premiums are missing the larger numbers. The "smarter" calculation is a comparison of annual small business insurance costs with the cost of a single loss.
What Is The Real Cost Of The Owner's Problem?
-
Premium vs. Claim: Calculate the annual premium against one realistic claim, covering defense costs, settlements, and extended downtime losses.
-
Claim Severity: Make estimates of the possible worst case for injury, property, or professional claims, relevant to your industry and activities.
-
Downtime Math: Determine the lost revenue from a day of downtime, and then multiply by reasonable recovery times in case of serious downtime.
-
Balance-Sheet Risk: Understand that cheap isn't cheap; poor quality can be a catastrophic financial risk right on the company's balance sheet.
How Can Business Owners Help Minimize The Risk Of Shutdowns?
The good news is that most shutdown scenarios are preventable! A focused review helps to cover what is current, covers the gaps before they are exposed in a loss, and helps align coverage with current operations.
What Are The Most Beneficial Business Actions To Take?
-
Exposure Review: Visualize exposure across operations, contracts, employees, vehicles, and data to identify all exposed liabilities.
-
Coverage Matching: Match every coverage to actual business operations rather than a single coverage assumption.
-
Endorsement Check: Check limits, exclusions, and endorsements before renewal to verify coverage responds when needed.
-
Growth Updates: Review coverage as services, personnel, vehicles, or new client contracts are added to the business during the year.
Conclusion: The Accident Is Small Until the Costs Start Compounding
A small accident can lead to medical costs, legal expenses, lost income, and operational disruption faster than many businesses expect. The strongest protection comes from carrying the right coverage, reviewing limits regularly, and making sure insurance reflects actual business operations.
To better understand your exposure and coverage options, connect with Insure Your Company. Our agents can help review your business accident risks and identify insurance that fits the way your company operates.
InsureYourCompany is a trusted Best IT business insurance company in NJ, offering customized coverage solutions to protect companies from financial and operational risks. We understand that every business has unique needs, which is why our expert insurance advisors design policies tailored to your industry and size. From general liability and workers’ compensation to commercial property and cyber insurance, we provide comprehensive protection for small and medium-sized businesses. Our goal is to ensure peace of mind while helping you stay compliant and secure. Partner with InsureYourCompany for reliable, affordable, and professional insurance services in NJ. Visit: https://insureyourcompany.com/
Comments (0)