Flood Insurance Companies in Florida Rarely Say This Out Loud
Ask around and you'll hear the same thing. Folks assume their homeowners policy has them covered, right up until the water comes in under the door. It doesn't. Never has. That's why the conversation about flood insurance companies in Florida matters more than most people realize, and why so many owners get it wrong the first time. They pick whoever quoted the lowest number, sign, and forget about it for a year. Then a storm hits and the fine print gets real fast. This post walks through what to look at, what to skip, and a few things agents don't always bring up unless somebody asks.
Florida Water Doesn't Follow the Rules
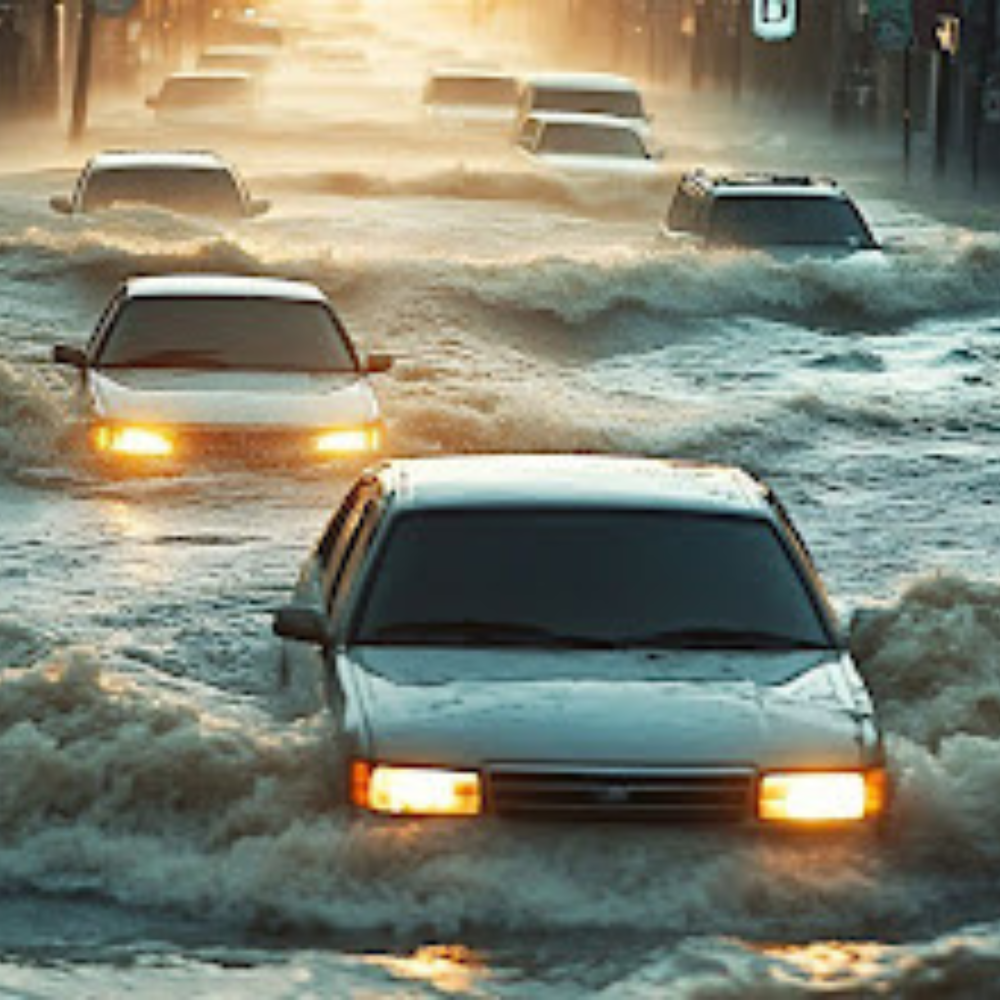
Water in Florida doesn't behave like water in other places. The ground is flat, the soil is sandy in some spots and packed hard in others, and the groundwater sits close to the surface. When it rains hard, it has nowhere to go. Storm drains built for a smaller town get overwhelmed, and streets turn into shallow rivers in an hour. Coastal owners worry about surge, which makes sense. But inland owners get hit too, and plenty of them never thought it could happen. Flood damage is one of the most common disasters in the state, and a big chunk of it lands on homes nobody labeled high risk. So no, living far from the beach doesn't get anyone off the hook.
Federal Policy or Private Coverage, Pick Carefully
There are basically two doors to walk through. The National Flood Insurance Program, run through FEMA, and private carriers who write their own policies. The federal one is standardized. Same coverage, same rules, whichever agent sells it. Private policies vary a lot more, and that's both the good news and the bad news. Some go beyond the federal limits, cover more types of property, or pay claims a bit differently. Others are stripped down and cheap for a reason. Private carriers can also decline a home outright or drop it later, which the federal program generally doesn't do. Truth is, plenty of owners end up using both, one for the base coverage and another to top it off.
How to Judge Flood Insurance Providers Beyond the Price
Price is the first thing people look at, and it's usually the wrong first thing. Look at how the company treats claims. Do reviews mention slow adjusters, lost paperwork, or surprise denials? Those stories pile up fast once a storm passes through. Check whether the company is financially solid, because a carrier that can't pay is worse than no carrier at all. Ask the agent how a claim actually works, step by step, and see if the answer is clear or vague. Pay attention to how fast they reply before you buy, since that's the best preview you'll get. Good flood insurance providers explain things plainly. Bad ones hurry you along.
Getting a Flood Zone Insurance Quote That Means Something
Here's where people rush, and it shows. A flood zone insurance quote is only as good as the info behind it. The agent needs the exact address, the zone on the current map, the elevation of the home, what the foundation looks like, when it was built, and whether there's a finished basement or an enclosure below the main floor. Small mistakes here can change the number later, and nobody likes a surprise at renewal. If the home has an elevation certificate, hand it over. If it doesn't, ask whether getting one could lower the cost. Get a few quotes side by side. And read what's excluded, not just what's included, because that's where the real differences hide.
Lenders, Maps and the Zones Everyone Mixes Up
Mortgage lenders care a lot about flood zones. If a home sits in a high risk area and the loan is federally backed, coverage is required, no debate. Those are the A and V zones. Zone X is lower risk, but lower isn't zero, and that's where people get comfortable and stay comfortable until it stops being true. Maps get redrawn too. A house that was outside the line at closing can end up inside it years later, and the lender sends a letter with a deadline. Owners who kept coverage going all along usually find that whole situation boring. Owners who didn't scramble. Look up the current map before buying, and again once in a while afterward.
Why the Bill Changes Year After Year
Flood premiums move, and the reasons aren't random. The federal program shifted to a newer pricing method that looks at how close a home is to water, how often that area floods, and what it would cost to rebuild. The older approach leaned mostly on the zone map. Some owners came out ahead. Others saw increases that keep stacking each year until they reach the full risk based price. It stings, let's be real. Private carriers price differently and sometimes more cheaply for well built or elevated homes. Deductibles matter too. Pick a high one and the premium drops, but the owner eats more after a loss, so it has to be something they can actually handle.
Waiting Periods, Contents and the Stuff People Forget
Most policies don't start the second someone pays. There's a waiting period, and buying after a storm shows up in the forecast is usually too late, apart from a few exceptions like closing on a home with a mortgage. That one catches people every year. Then there's content coverage, which often gets skipped even though furniture, appliances and clothes add up in a hurry. Some things, like landscaping or vehicles, aren't covered at all, and owners get frustrated when they find out. Keep a home inventory. Take photos, walk room to room with a phone. Store them somewhere that isn't the house. And mark the renewal date, because a lapse can undo years of good planning.
Choosing Flood Coverage Without the Guesswork
So what's the takeaway? There's no one perfect pick, and anybody who claims otherwise is selling something. The smart route is simple even if it takes some effort. Compare the federal program with private options, look hard at claims reputation, and request a real flood zone insurance quote using accurate details, not rough guesses. Ask blunt questions about exclusions and how long coverage takes to begin. Start well before hurricane season, not during it. The best of the flood insurance carriers in the state is the one that fits a particular home, a particular budget and a particular tolerance for risk. Water doesn't wait for anybody to get organized. Get it done early.
Comments (0)