Personal Loan Rejected? Top 10 Reasons Banks and NBFCs Say No
Personal loan rejected? Learn 10 common rejection reasons, from credit score and high EMIs to income, documents and lender eligibility.
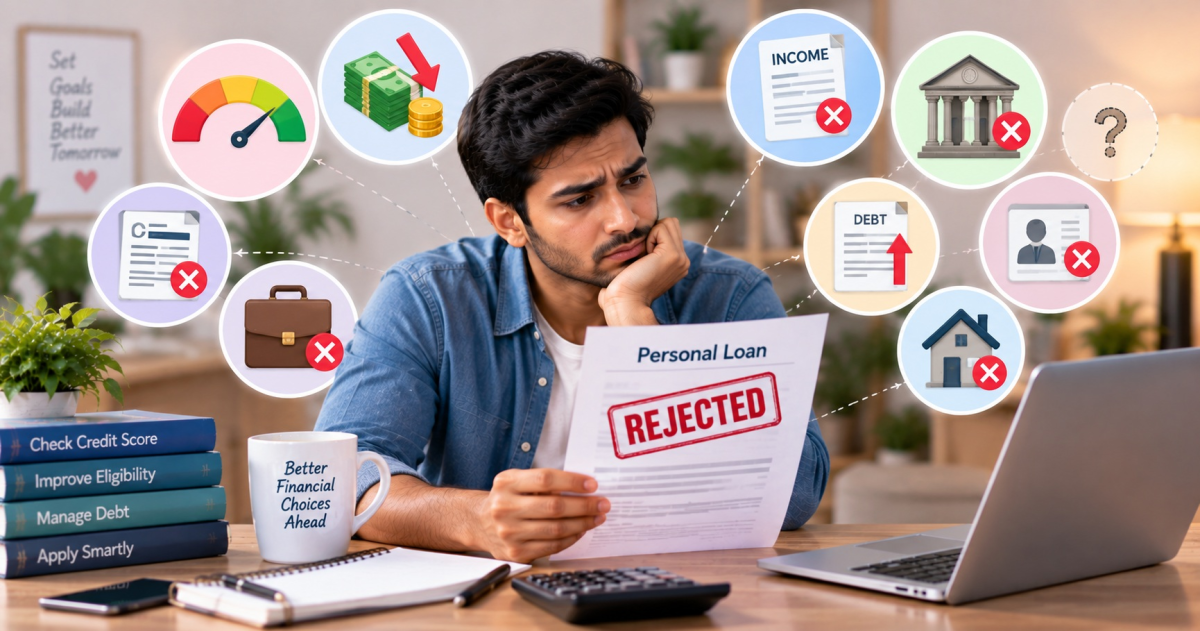
A personal loan rejected message can be frustrating, especially when you were expecting approval. Banks and NBFCs assess several factors before approving an unsecured loan, including income, credit history, existing debt, employment profile, application details and internal lending policies.
If you are wondering why personal loan gets rejected, there is usually more than one possible explanation. A lender may consider your income insufficient for the requested amount, identify a high existing debt burden, find inconsistencies in your application or decide that your credit profile does not meet its current eligibility criteria.
The good news is that a rejection does not necessarily mean you cannot get a personal loan in the future. Understanding the personal loan rejection reasons can help you identify what needs to be improved before submitting another application.
10 Common Personal Loan Rejection Reasons
1. Low Credit Score or Weak Credit History
Your credit history is one of the factors lenders may consider when evaluating an unsecured personal loan application.
A history of missed payments, defaults, settlements or consistently high credit utilisation can make an application less attractive to some lenders.
However, there is no single credit score that guarantees approval across all banks and NBFCs. Each lender can use its own underwriting criteria.
If your personal loan is rejected because of credit score, check your credit report for:
-
Missed or late payments
-
Accounts incorrectly reported
-
High outstanding balances
-
Loan accounts shown as overdue
-
Multiple recent credit enquiries
-
Settled or written-off accounts
Correcting genuine errors in your credit report can be an important first step.
2. Income Is Too Low for the Requested Loan
Another common personal loan rejection reason is insufficient income relative to the amount requested.
Personal loans are generally unsecured, so lenders need to assess whether your income can support the proposed EMI along with your existing financial commitments.
For example, someone earning ₹25,000 per month may have difficulty qualifying for a large loan if the resulting EMI would take up a substantial portion of their monthly income.
This does not mean a particular income automatically qualifies or disqualifies you. Lenders can have different minimum income requirements and affordability calculations.
What can help?
You may consider:
-
Applying for a smaller loan amount
-
Choosing a longer repayment tenure where appropriate
-
Reducing existing debt
-
Improving your documented income profile
3. High Existing EMI Obligations
Suppose you already have:
-
Home loan EMI
-
Car loan EMI
-
Credit card EMI
-
Consumer durable loan
-
Existing personal loan
Adding another EMI increases your overall debt obligation.
Lenders may calculate your debt-to-income or fixed-obligation-to-income ratio as part of their assessment.
If your existing obligations already consume a large portion of your income, the lender may reject the new application.
This is one reason why personal loan applications get rejected despite having a regular salary.
4. Unstable Employment History
Lenders may consider employment stability when assessing salaried applicants.
Frequent job changes, a very short employment period or insufficient tenure with the current employer may affect eligibility for certain loan products.
Requirements vary between lenders. Some may specify minimum employment or work experience criteria, while others may evaluate the overall profile.
If you recently changed jobs, checking the lender's current employment criteria before applying can help avoid unnecessary applications.
5. Inconsistent Income or Employment Information
Information provided in your application may be checked against supporting documents and information available to the lender.
For example, discrepancies between:
-
Salary declared in the application
-
Salary reflected in bank statements
-
Employer information
-
Address details
-
Employment duration
-
Income documents
can raise questions during verification.
If the lender cannot verify the information provided, the application may not proceed.
Always provide accurate information and make sure your supporting documents are current.
6. Too Many Recent Loan or Credit Applications
Every credit application can potentially result in a credit enquiry.
Applying for several personal loans or credit cards within a short period can create multiple recent enquiries on your credit report.
Multiple applications do not automatically mean your loan will be rejected, but they can form part of the lender's assessment of your credit-seeking behaviour.
If your personal loan was rejected, avoid immediately submitting applications to numerous lenders at the same time.
Instead, understand the likely reason for the rejection and address it before applying again.
7. Poor Repayment History
A history of missed EMI or credit card payments can negatively affect your credit profile.
Even if your current salary is sufficient, a lender may consider previous repayment behaviour when evaluating a new application.
For example, if your credit report shows repeated late payments, the lender may consider the application higher risk.
How to improve your repayment history
-
Pay EMIs before the due date
-
Pay credit card bills on time
-
Avoid allowing accounts to become overdue
-
Set up payment reminders or automatic payments
-
Review your credit report regularly
Building a stronger repayment record takes time. There is no instant method that can guarantee approval.
8. Incorrect or Incomplete Documents
A loan application can also face problems when required documentation is missing, outdated or inconsistent.
Depending on the lender and applicant, documents can include:
-
PAN
-
Identity proof
-
Address proof
-
Salary slips
-
Bank statements
-
Form 16
-
Income-tax documents
-
Employment information
Self-employed applicants may have different documentation requirements from salaried applicants.
Before applying, check the lender's current document requirements and submit accurate information.
9. Applying for a Loan That Does Not Match Your Profile
Different lenders target different customer segments.
A loan product may have specific eligibility criteria based on:
-
Age
-
Income
-
Employment type
-
Location
-
Employer category
-
Existing banking relationship
-
Credit profile
-
Requested loan amount
For example, a lender may have a minimum monthly income requirement or only serve applicants in selected locations.
Therefore, personal loan eligibility should be checked before completing an application.
10. Internal Bank or NBFC Credit Policy
Sometimes you may meet the publicly stated eligibility criteria and still receive a rejection.
Why?
Because eligibility criteria displayed on a lender's website are not necessarily the only factors used for final underwriting.
Banks and NBFCs may use internal credit policies, risk models, verification results and other information when making lending decisions.
This means that meeting the minimum age and income criteria does not guarantee approval.
Why Was My Personal Loan Rejected Even With a Good Credit Score?
A good credit score can help, but it is not the only factor lenders consider.
Your application could still be rejected because of:
-
High existing EMIs
-
Insufficient income for the requested amount
-
Short employment history
-
Inconsistent documents
-
Internal lender policies
-
Recent credit enquiries
-
Employer or location criteria
-
Verification issues
Therefore, personal loan rejected despite good CIBIL score is possible.
Credit score should be viewed as one part of the overall lending assessment rather than a guaranteed approval threshold.
What Does "Loan Rejected After Approval" Mean?
Sometimes borrowers search for loan rejected after approval because their application initially appeared approved but the final disbursement did not happen.
This can occur when approval is conditional or subject to additional verification.
For example, a lender may still need to complete:
-
Document verification
-
Income verification
-
Employment verification
-
KYC checks
-
Final credit assessment
A preliminary or conditional approval should therefore not always be interpreted as guaranteed disbursement.
If a lender withdraws or changes an approval, ask the lender for the specific reason and understand whether additional documentation is required.
What to Do After a Personal Loan Rejection
If your application has been rejected, avoid immediately applying everywhere.
Instead, follow these steps.
Step 1: Find Out the Reason
Contact the lender and ask whether they can provide the reason or relevant category for rejection.
Step 2: Check Your Credit Report
Look for:
-
Incorrect personal information
-
Unrecognised accounts
-
Late payments
-
High outstanding balances
-
Multiple recent enquiries
If you find an error, raise a dispute with the relevant credit bureau and lender.
Step 3: Review Your Existing Debt
Calculate your current monthly EMI obligations and compare them with your income.
If existing debt is high, reducing outstanding balances may strengthen your affordability profile over time.
Step 4: Reconsider the Loan Amount
If your income does not comfortably support the requested EMI, a smaller loan amount may be more appropriate.
Step 5: Avoid Multiple Applications
Do not submit applications to many lenders simply because the first application was rejected.
Compare eligibility first and apply selectively.
How to Improve Personal Loan Eligibility
If you want to improve personal loan eligibility, focus on factors you can realistically control.
Maintain Timely Payments
Pay all existing EMIs and credit card bills on time.
Reduce Existing Debt
Lower outstanding debt where financially possible.
Keep Credit Utilisation Under Control
Avoid relying heavily on your available revolving credit limit.
Maintain Stable Financial Records
Keep your bank statements, income documents and employment information accurate and organised.
Apply for a Suitable Amount
A loan amount that matches your income and repayment capacity may be more appropriate than applying for the maximum amount available.
Check Eligibility Before Applying
Review the lender's current requirements before submitting a formal application.
Can You Apply Again After a Personal Loan Rejection?
Yes, you can apply again, but timing matters.
Applying again immediately without addressing the reason for rejection may lead to another unsuccessful application.
For example, if your application was rejected because your existing EMI burden was high, simply applying to another lender for the same amount may not solve the underlying problem.
Instead:
Rejection → Identify reason → Improve profile → Check eligibility → Apply selectively
This approach can help you avoid unnecessary applications.
Personal Loan Rejection: Quick Checklist
Before applying again, check:
| Factor | What to Review |
|---|---|
| Credit history | Any missed payments or defaults? |
| Income | Is it sufficient for the requested amount? |
| Existing EMIs | How much of your income is already committed? |
| Employment | Do you meet the lender's tenure requirements? |
| Documents | Are all documents accurate and current? |
| Credit enquiries | Have you applied for multiple loans recently? |
| Loan amount | Does it match your repayment capacity? |
| Eligibility | Do you meet the lender's current criteria? |
FAQs
Why does a personal loan get rejected?
Common personal loan rejection reasons include weak credit history, insufficient income, high existing EMI obligations, unstable employment, documentation issues, multiple recent credit applications and lender-specific internal policies.
Can I get a personal loan after rejection?
Yes, you may be able to apply again after addressing the reason for rejection. Approval depends on the lender's eligibility and underwriting criteria.
Why was my personal loan rejected despite a good CIBIL score?
A good credit score does not guarantee approval. Lenders may also consider income, existing debt, employment history, documents, recent credit enquiries and internal risk policies.
Does loan rejection affect CIBIL Score?
A formal credit application may result in a hard enquiry, which can appear on your credit report. The rejection itself is not the same thing as a negative credit account, but multiple recent enquiries can be considered as part of your overall credit profile.
How can I improve personal loan eligibility?
You can work on timely repayment, reducing existing debt, maintaining accurate income documentation, controlling credit utilisation and applying for a loan amount that fits your repayment capacity.
How long should I wait after a personal loan rejection?
There is no universal waiting period. The appropriate timing depends on the reason for rejection. If the issue is high debt, insufficient income documentation or credit-report errors, address that issue before applying again.
Can a bank reject a loan after initial approval?
Yes. If an initial approval is conditional, final verification and underwriting may still be required before disbursement. Ask the lender for clarification if the status changes.
Final Takeaway
A personal loan rejected status does not necessarily mean you are permanently ineligible for credit. Banks and NBFCs assess multiple factors, and the reason for rejection can vary from one applicant to another.
The most useful response is to identify the specific issue rather than applying repeatedly. Check your credit report, review your existing EMI obligations, verify your income documents and make sure the requested loan amount fits your repayment capacity.
Before applying again, compare lender eligibility criteria and choose an amount that aligns with your financial profile.
BankCreds provides financial comparison and educational information. Loan approval, interest rates, eligibility, documentation requirements and loan amounts are determined by individual banks and NBFCs. Comparison does not guarantee approval.
BankCreds helps consumers explore and compare loan options from different lenders. The platform provides loan eligibility guidance, EMI planning tools, credit insights, lender information, and educational resources to simplify financial decision-making. BankCreds does not directly provide loans; it helps users understand their options before applying. For More Details Please Visit https://bankcreds.com/
Comments (0)