Business Loan for Self-Employed: Eligibility, Income Proof & Documents
Learn about business loan for self employed applicants, eligibility, income proof, required documents, loans without salary slips, and application tips.
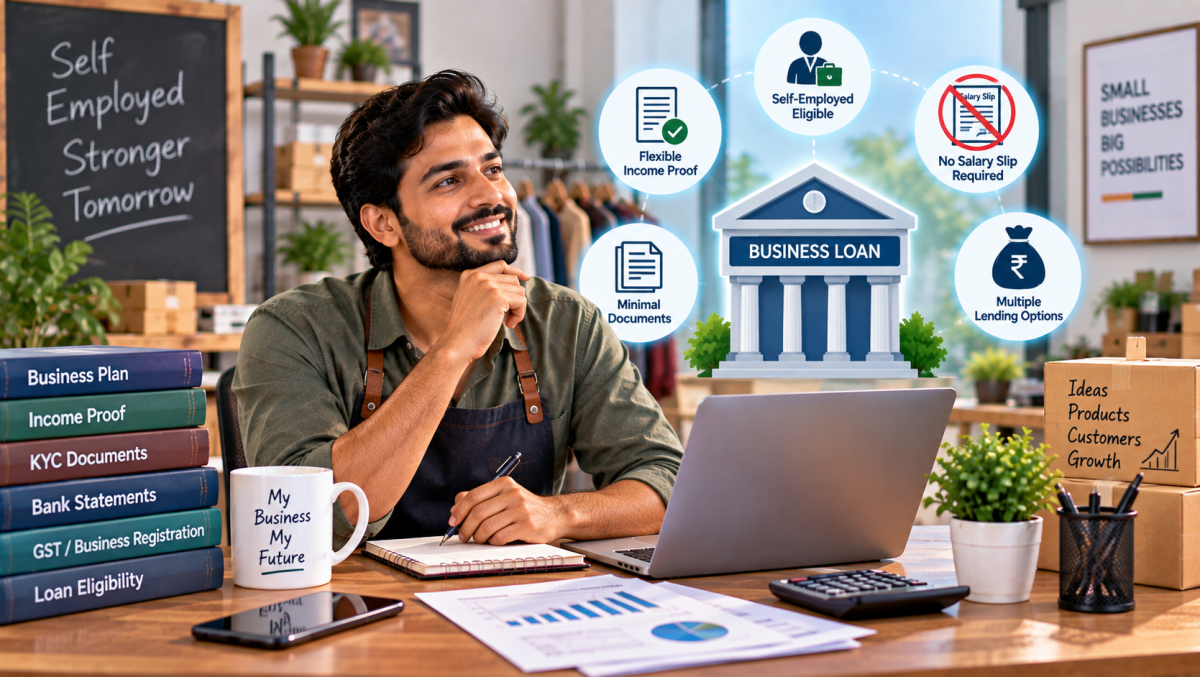
Getting a loan can look different when you work for yourself. Unlike salaried employees who can provide salary slips and employer certificates, self-employed professionals and business owners usually prove their income through bank statements, income tax returns, GST records, and business financial documents.
A business loan for self employed can help fund working capital, inventory, equipment, expansion, marketing, technology, or other business expenses. However, lenders generally assess the business and borrower's financial profile before deciding eligibility and loan terms.
If you are looking for a self employed business loan India, understanding the eligibility requirements and income documents beforehand can make the application process easier.
Can Self-Employed People Get a Business Loan?
Yes. Self-employed individuals can apply for business loans from banks, NBFCs, and other regulated lenders, subject to their eligibility criteria.
A self-employed applicant may include:
-
Business owners
-
Sole proprietors
-
Partners in a business
-
Freelancers
-
Consultants
-
Professionals
-
Traders
-
Manufacturers
-
Service providers
The lender may assess factors such as business vintage, turnover, profitability, banking history, credit profile, and repayment capacity.
Unlike a salaried applicant, the focus may be less on a fixed monthly salary and more on the overall financial performance of the business or profession.
Business Loan Eligibility for Self-Employed
Self employed loan eligibility varies between lenders and loan products. However, common factors include the following.
Business Vintage
Lenders may require the business to have been operating for a minimum period. The exact requirement depends on the lender.
A longer operating history can provide more financial information for assessing the business.
Credit History
Your personal and, where applicable, business credit history can influence the lending decision.
A record of timely repayment on existing loans and credit facilities can help demonstrate responsible borrowing behaviour.
Income and Cash Flow
Lenders generally want to understand whether the business generates enough income to support the proposed loan repayment.
This is why bank statements, tax returns, and financial statements can be important for self-employed borrowers.
Turnover and Profitability
Some lenders may consider business turnover, profitability, and other financial indicators.
High turnover alone does not necessarily mean that a business can comfortably repay a loan. Lenders may also examine expenses, existing liabilities, and cash flow.
Existing Financial Obligations
If you already have loans or credit facilities, the lender may consider your existing repayment commitments when assessing the new application.
Business Loan Without Salary Slip
One common misconception is that you need a salary slip to obtain business financing.
A business loan without salary slip is possible because self-employed applicants generally do not receive traditional salary slips.
Instead, lenders may use alternative income documents to understand the applicant's earnings and repayment capacity.
Depending on the lender, these may include:
-
Income tax returns
-
Bank statements
-
GST returns
-
Profit and loss statements
-
Balance sheets
-
Business registration documents
-
Other financial records
The exact documents required depend on the lender and the applicant's business structure.
What Can Be Used as Business Loan Income Proof?
Business loan income proof is particularly important for self-employed applicants because their income may vary from month to month.
Common forms of income evidence can include:
Income Tax Returns
ITRs can help demonstrate reported income over previous financial years.
Bank Statements
Bank statements can show business receipts, expenses, cash flow, and regular financial activity.
GST Returns
For businesses registered under GST, applicable GST returns can provide information about reported business activity.
Financial Statements
Depending on the business and lender, documents such as profit and loss statements and balance sheets may be requested.
Business Receipts and Invoices
For certain applicants, invoices, payment records, or other evidence of business income may help establish revenue.
The lender decides which documents are acceptable.
Documents for Business Loan
The exact documents for business loan applications vary, but self-employed applicants may commonly be asked for:
-
PAN card
-
Aadhaar or other identity proof
-
Address proof
-
Bank statements
-
Income tax returns
-
GST registration and returns, where applicable
-
Business registration documents
-
Profit and loss statements
-
Balance sheets
-
Partnership deed, if applicable
-
Certificate of incorporation, if applicable
-
Business address proof
-
Details of existing loans or liabilities
A sole proprietor may have different documentation requirements from a private limited company or partnership firm.
Business Loan for Different Types of Self-Employed Applicants
Self-Employed Business Owners
Business owners may use financing for inventory, working capital, expansion, equipment, or other operational requirements.
Freelancers and Consultants
Freelancers may need funding for computers, software, marketing, office setup, or business expansion. Their bank statements and tax returns can be particularly useful for demonstrating income.
Traders
Traders may require short-term working capital to purchase inventory and manage the gap between purchases and customer payments.
Professionals
Doctors, architects, lawyers, accountants, designers, and other professionals may seek funding for office expansion, equipment, technology, or other professional expenses.
How to Improve Self-Employed Business Loan Eligibility
If you are planning to apply for a business loan for self employed, prepare your financial records before submitting the application.
Maintain Separate Business Banking
Keep business transactions organised and, where practical, separate from personal spending. This makes cash flow easier to understand.
File Tax Returns Regularly
Keep applicable income tax filings up to date and ensure that reported income is consistent with your financial records.
Maintain GST Records
If GST registration applies to your business, keep returns and supporting records organised.
Check Your Credit Report
Review your credit history before applying. Look for errors, overdue accounts, or other issues that may need attention.
Reduce Unnecessary Existing Debt
High existing obligations can affect your repayment capacity. Review current EMIs and credit commitments before taking on additional borrowing.
How Much Business Loan Can a Self-Employed Person Get?
There is no single loan amount available to every self-employed applicant.
The amount may depend on:
-
Business income
-
Turnover
-
Profitability
-
Banking history
-
Credit profile
-
Existing EMIs
-
Business vintage
-
Loan tenure
-
Repayment capacity
-
Lender's internal policies
Instead of focusing only on the maximum amount offered, calculate how much funding your business actually needs.
For example, if you need funds for inventory worth ₹5 lakh, taking a significantly larger loan simply because you qualify for it may increase your repayment burden unnecessarily.
What Should You Compare Before Taking a Business Loan?
Do not compare loans only by the advertised interest rate.
Check:
| Factor | Why It Matters |
|---|---|
| Interest rate | Determines borrowing cost |
| Processing fee | Adds to the total cost |
| Loan tenure | Changes the monthly repayment |
| EMI | Helps assess cash-flow impact |
| Prepayment terms | Important if you plan early repayment |
| Late-payment charges | Can increase costs |
| Loan amount | Should match your actual requirement |
| Documentation | Affects application preparation |
Also understand whether the quoted interest rate is fixed or floating and how the lender calculates applicable charges.
Common Mistakes Self-Employed Borrowers Should Avoid
Before applying for a self employed business loan India, avoid these common mistakes:
-
Providing inconsistent income information
-
Not keeping bank statements ready
-
Ignoring tax filings
-
Applying without checking eligibility
-
Taking a larger loan than required
-
Ignoring processing and other fees
-
Hiding existing financial obligations
-
Submitting incomplete documents
-
Applying to multiple lenders without comparing their requirements
Accurate documentation can help reduce unnecessary delays during the application process.
Final Takeaway
A business loan for self employed applicants does not necessarily require a traditional salary slip. Banks and NBFCs can use other financial records to understand business income and repayment capacity.
ITRs, bank statements, GST records, financial statements, and business documents can all play a role depending on the lender.
If you are planning to apply, first understand your self employed loan eligibility, organise your business loan income proof, and prepare the required documents for business loan applications.
Most importantly, borrow based on your actual business requirement and expected repayment capacity rather than simply choosing the highest amount available.
FAQs
Can a self-employed person get a business loan?
Yes. Self-employed business owners, professionals, freelancers, traders, and other eligible applicants can apply for business loans, subject to the lender's eligibility criteria.
Can I get a business loan without a salary slip?
Yes. Self-employed applicants generally do not have salary slips. Depending on the lender, income may instead be assessed using ITRs, bank statements, GST records, and financial statements.
What income proof is required for a self-employed business loan?
Common documents can include ITRs, bank statements, GST returns, profit and loss statements, balance sheets, invoices, and other financial records. Requirements vary by lender.
What documents are needed for a business loan?
Documents may include identity and address proof, PAN, bank statements, tax returns, GST records, business registration documents, financial statements, and other lender-specific documents.
How is self-employed loan eligibility calculated?
Eligibility can depend on business income, turnover, profitability, credit history, business vintage, existing financial obligations, and repayment capacity. Each lender can use its own assessment criteria.
Can freelancers apply for business loans?
Freelancers may apply for business financing if they meet the lender's requirements. ITRs, bank statements, invoices, and other records can help demonstrate professional income.
How can I improve my chances of getting a business loan?
Maintain accurate financial records, file applicable tax returns on time, keep banking activity organised, monitor your credit profile, reduce unnecessary debt, and apply for an amount that matches your business requirement and repayment capacity.
BankCreds helps consumers explore and compare loan options from different lenders. The platform provides loan eligibility guidance, EMI planning tools, credit insights, lender information, and educational resources to simplify financial decision-making. BankCreds does not directly provide loans; it helps users understand their options before applying. For More Details Please Visit https://bankcreds.com/

Comments (0)