Profit and Loss Statement: A Simple Guide for Businesses
One of the most helpful financial statements to have to understand the operations of a business is a profit and loss statement.
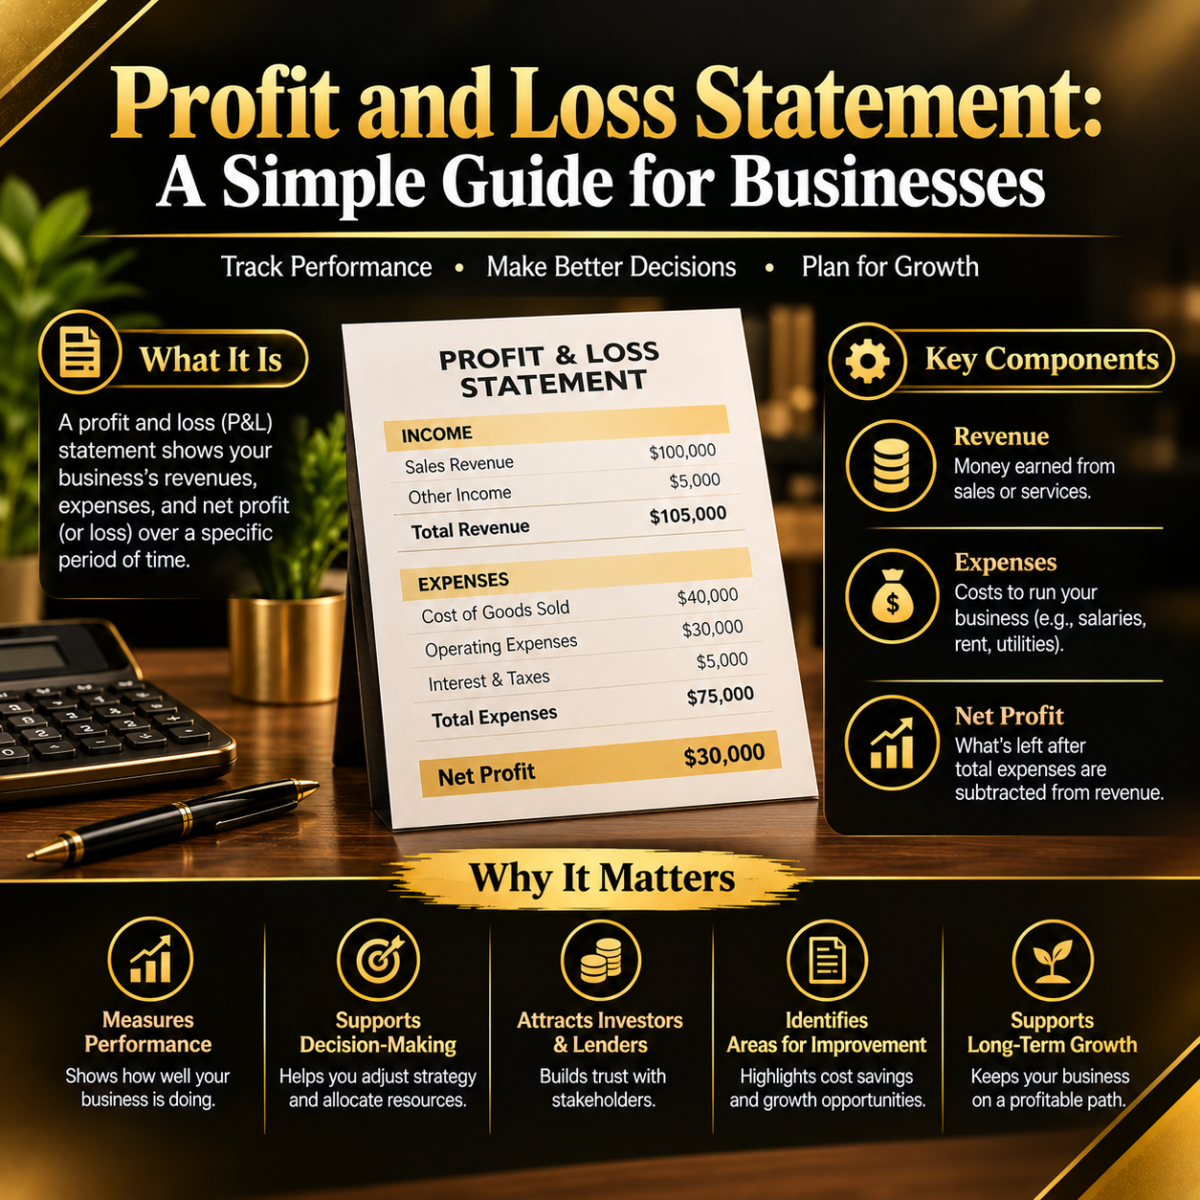
One of the most helpful financial statements to have to understand the operations of a business is a profit and loss statement. It reflects the revenue that a company generates, its expenses incurred, and the net profit or loss for a particular time frame. If you wonder what is a profit and loss statement, it is just a financial statement which summarizes the income of the business and losses.
A Profit and Loss Statement, commonly referred to as a P&L statement, may be produced monthly, quarterly or annually. Regularly examining the profit and loss statement will help the business owner determine if the company is generating profits, rising costs or declining profits. This information can also alert management to monetary issues that are able to become tougher to manage.
What Is a Profit and Loss Statement?
Thus, what is a profit loss statement? It is a report which compares the revenue of the business with its expenses of the business over a specific period of time. If the company makes more money than it spends, it will post a profit. If the business incurs more costs than income, then the business has a loss.
It's quite easy to define the basic p&l. A profit loss statement offers the user a view of performance in the business, and helps to explain where the money was spent and where it has gone. This could be sales, cost of goods, payroll, rent, utilities, marketing, depreciation, interest and other operating expenses.
Profit & loss statement, profit & loss report and profit & loss account are possible synonyms for this financial reporting. In most cases, the income statement and the profit and loss statement mean the same thing.
This also clarifies another frequently asked question, ‘Is profit and loss similar to the income statement? Generally, yes. The term income statement is the more common term used in accounting, while profit and loss statement or P&L statement is more popular for businesses.
Understanding Profit and Loss and Write-Offs
When examining the profits and losses over time, business owners can discover significant trends in the financial aspects of their business. For instance, while the sales increase might seem good, the operating costs could increase at the same time, which means that there is less profit. Monthly or quarterly analysis of results may offer a better picture of performance in the business.
Another word that can be misleading is write-off. Individuals may wonder what is meant by profit and loss write off or what is a profit and loss write off? In accounting, a write-off is the process of eliminating an asset, expense or sum that no longer has a reasonable expectation of being recovered, following any relevant accounting or tax regulations. The treatment will vary according to the specific item being written off.
A well prepared profit and loss statement provides useful information for budgeting, planning and financial decision making for the business owner. It can also be used to highlight waste and where the business can make some improvements to make it more profitable.
A profit and loss statement, also known as a profit and loss account, P&L or an income statement, is a document designed to show a business's income, expenses, profit and loss for a specific time. Regularly checking this report will enable businesses to be aware of their financial standing and make informed decisions.
For more details visit us - https://accountance.net/
Comments (0)