Common Insurance Compliance Challenges and How Agents Can Avoid Them
Insurance is among the industries that is most closely regulated across the globe and it's not without reason. Insurance policyholders trust their agents to provide delicate financial information, life-altering decisions, and promises of security. This trust is reinforced by a tangled web of federal and state regulations designed to keep the business honest and transparent. Agents, however this regulatory landscape could feel like a maze. One misplaced disclosure or license that is expired or an unprofessionally written email could be an actual violation of compliance with reputational and financial consequences.
The good news is that the majority of compliance problems aren't the consequence of a bad intention. They're caused by gaps in processes or outdated systems, or a simple oversight. Recognizing the areas where these gaps commonly are can be the initial step towards getting them closed. Here, we discuss the most frequent issues that insurance companies confront today, as well as ways to prevent them.
1. Licensing and Continuing Education Lapses
Each state is governed by its unique set of rules regarding who is able to sell insurance, what levels of authority they require and when they need to keep their licences up to date. Agents working across several states -- something that is becoming more frequent with remote sales and marketing via digital -must keep track of the various renewal dates as well as the requirement for continuing educational (CE) requirements and appointment regulations for every carrier they represent.
What causes it: Licenses often renew with a rolling calendar that is linked to the month of birth or the date on which they first issued and not just a single date on a calendar. Agents who hold licenses across more than six states, it's not difficult to forget the next due date.
How to prevent it:
-
Utilize a platform for managing licensing or a shared calendar of compliance which flags renewal dates for 90 60, 30 and 30 days out.
-
Complete CE credits prior to the renewal cycle, rather than waiting for the deadline because the timing of processing and availability of courses may vary.
-
Audit your carrier appointments regularly to ensure they are in line with your current licenses in force particularly after you have added an additional state or line of authority.
2. Inadequate or Inconsistent Disclosures
Disclosure requirements are required to ensure that clients know what they're purchasing as well as the cost as well as any conflict of interests the agent may have, for example, commission structures or connections to a specific company. The absence of or inconsistency of disclosures is among the top problems in state insurance department audits.
The reason it happens is: Disclosure requirements vary depending on the product type (life annuities, health and property/casualty) and also by the state. Agents who sell multiple products may accidentally apply the wrong disclosure standards or miss a necessary form in a rapid sales discussion.
How to get rid of it:
-
Develop disclosure checklists for every product line and state and then integrate the checklists directly into sales workflows or CRM systems so that they won't be missed.
-
Standardize written and scripted materials so that verbal and written disclosures are exactly the same.
-
Record every disclosure discussion including the date, time, method (phone or email or in person) and any materials that were provided.
3. Data Privacy and Cybersecurity Gaps
Insurance agents manage one of the more sensitive private information available: Social Security numbers, financial records, medical histories and beneficiary details. Privacy regulations for data (including specific laws for each state based on models like the NAIC Insurance Data Security Model Law have been progressively holding companies accountable not just for data breaches, but also for not having adequate security measures initially.
What causes it: Many independent agents and small-sized agencies still depend on unsecure emails, spreadsheets, shared or obsolete software to save client information, just because it's convenient or easy.
How to prevent it:
-
Make use of encrypted, specially-designed systems (CRM or software for managing agencies) to store and transfer client information, not common email and shared drives.
-
Set up multi-factor authentication for any system that touches the client's information.
-
Develop an incident response plan in writing to ensure that, if there is a breach the agency is able to respond within the timeframes the majority of states have.
-
Training staff on the recognition of phishing scams and safe methods of handling data, as human error is still the main source of data security breaches.
4. Misrepresentation and Unsuitable Recommendations
Regulators are attentive to ensure that the products they suggest are suitable for the customer's stated requirements, income, and risk tolerance. This is particularly true of life insurance and annuities, in which "suitability" and "best interest" standards have been heightened in recent years, following changes in the National Association of Insurance Commissioners' Suitability in Annuity Transactions Model Regulation.
The reason it happens: Sales pressure, incentive structures, or simply going too quickly through a customer conversation may cause agents to suggest an item that technically meets the requirements of an assessment, but isn't in the best interests of the customer.
How to prevent it:
-
Utilize a documented process for needs analysis for each sale, not only for complicated products such as annuities. Write down the customer's objectives as well as their financial situation and their risk tolerance in writing prior making a recommendation for an item.
-
Don't present the only highest-commission alternative; explain why other options were considered, but not ruled out.
-
Note down in detail the reasons behind every suggestion, since the rationale that is well-documented is usually the most effective defense in a dispute over suitability.
5. Advertising and Marketing Violations
Marketing is where many compliance concerns start, particularly when agents rely more on the internet for their marketing. The state insurance department closely controls the manner in which policies are advertised and what claims are made, and the manner in which testimonials or guarantees are displayed.
The reason for this is: Marketing content is usually created in a hurry, and often by freelancers or agencies that are not familiar with the insurance-specific rules on advertising. A language that would be acceptable in other industries -for example "guaranteed savings" or an unqualified "best rate" claim -could be a cause for violations in insurance-related advertising.
How to prevent it:
-
All marketing materials, such as website content, emails and social media posts through a review of compliance prior to the publication.
-
Keep a record of all claims and language that have been reviewed in order that writers and marketers don't have to reinvent the wheel every time.
-
Beware of testimonials from customers and reviews. Certain states have specific limitations for testimonials when they are used in advertising for insurance.
6. Poor Record-Keeping and Documentation
The majority of compliance investigations rely on documents. If an agent doesn't have documents that show what was revealed or recommended and what was accepted by regulators and judges tend to go with the client. Records-keeping requirements usually span several years and encompass applications and disclosures, correspondence and internal notes.
The reason it happens: Agents often keep documents informally -- for example, in personal emails, files on paper or notes scattered throughout -which can make retrieval difficult and increases the likelihood that the records will be lost, especially during employee shifts.
How to prevent it:
-
All client documentation should be centralized within a single system that has consistency in naming conventions as well as retention schedules that align with the requirements of your state.
-
Backup records frequently and make sure that access controls are in place so that documents aren't altered in the future.
-
Conduct internal audits on a regular basis of client records to identify the gaps before a regulator notices them.
7. Failure to Keep Up With Changing Regulations
Insurance regulations aren't fixed. Standards for suitability and the privacy of data, AI-assisted subwriting and remote sales practices have all changed dramatically during the past few years. A salesperson who believes that the compliance education of last year is still in place could be operating under outdated assumptions.
The reason it happens: Compliance training is typically viewed as a one-time onboarding procedure instead of an ongoing obligation particularly in smaller organizations that do not have a dedicated compliance manager.
How to prevent it:
-
Get the latest news by your insurance state department as well as the NAIC and assign a person within the agency to oversee the regulatory changes.
-
Set up recurring (not only annual) compliance refreshers, especially after major updates to the regulatory framework.
-
Join networks or associations that provide timely guidance on compliance specifically tailored to the state you are in and the product lines.
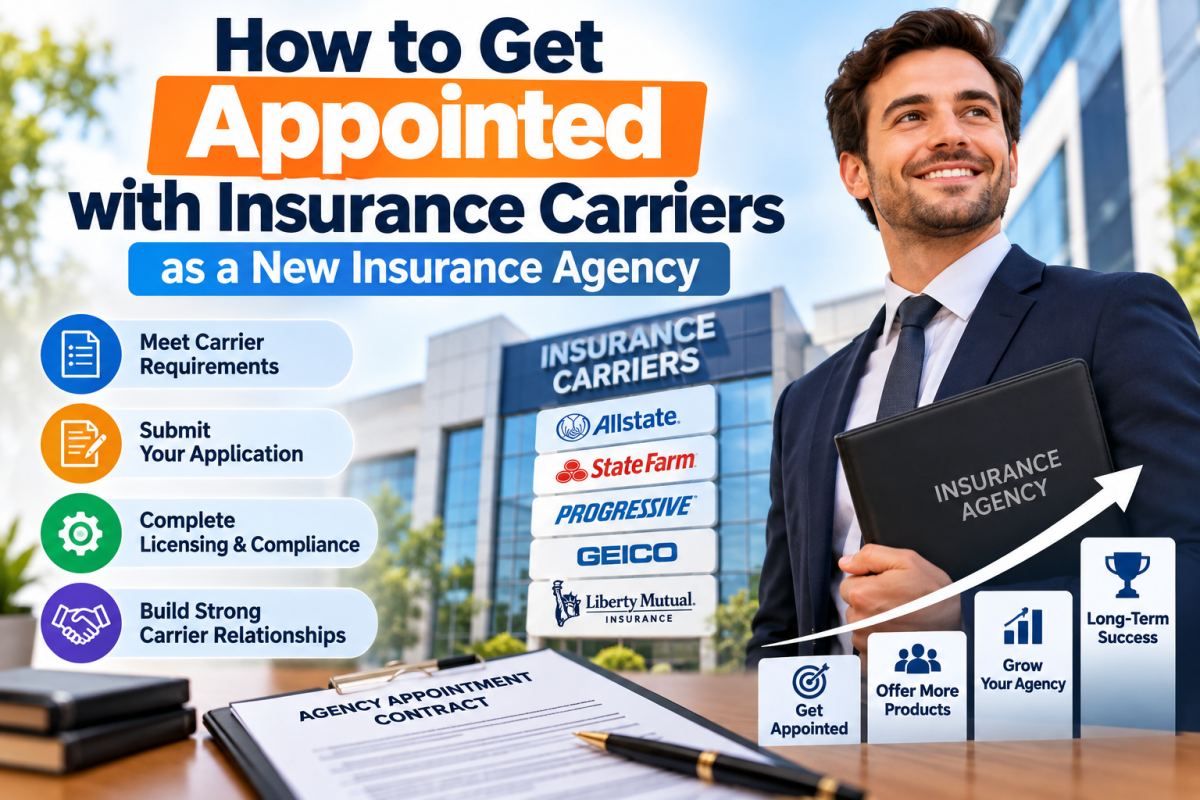
Also Read This Blog Now: How to Get Appointed with Insurance Carriers as a New Insurance Agency
Building a Culture of Compliance, Not Just a Checklist
The agencies and agents that manage compliance the best tend to approach it as an ongoing process instead of a once-a-year exercise. That's why they integrate checks for compliance directly into daily workflows, such as the calendars for licensing, templates to disclose marketing review procedures as well as secure systems for data to ensure that adhering to the guidelines becomes the route that is least difficult, and not an additional step which is easy to forget when pressure is on.
It's also about creating an environment that allows employees to feel confident flagging any uncertainty instead of thinking about it. A simple question to a compliance official or a quick check against a checklist will be far more affordable than a breach found months later in an audit.
In the end, strict compliance policies protect more than just the license of the agency. They also protect client relationships and the trust that the whole business is built upon. The agents who have clear procedures, continuous education, and a meticulous record of their activities don't just avoid penalties but they're creating an image that keeps customers coming back and referring to their friends for many years to be.
Apexwise Insurance Group delivers complete support solutions for insurance agents and businesses. From Agent Contracting and Compliance Support to CRM & Back Office management and Training & Growth, we provide the resources needed to grow in today's competitive insurance industry.
Comments (0)